Self-provision

Pension insurance: time is your greatest capital

In pension savings, the most expensive thing is postponing. A 20% annual tax credit (up to a cap, against the personal income tax actually paid), a lock-in that protects you from raiding the pot – and a plan tailored to your own rhythm.

Snowball Run

Mini game · 30 seconds

🎮 Snowball Run – 30 seconds = 30 years

Why with me?

Compound interest

The earlier you start, the longer your savings have to work – years started early are hard to make up for later. I don't promise a specific ratio or amount: the final result depends on the plan you choose, the premium and the returns, and the return is not guaranteed.

State tax credit

20% of your payments comes back as a credit (up to an annual cap, against the personal income tax actually paid) – few gifts like this exist.

Transparent terms

Costs, terms, flexibility – compared, in plain words, with no overpromising.

How does it work?

A conversation

20 minutes by phone or video: your situation, your goals, your budget. Free of charge, with no obligation.

Competition

I collect offers from the relevant insurers and hand them over in a single, easy-to-read table – strengths and weaknesses included.

Decision & beyond

You decide, I handle the paperwork. If you have a question later or your situation changes, let me know – and when a claim comes, I help you get started.

Insights – 95 plain-language articles

The former Guides have grown into a full library: basics, the tax credit and its rules, types and costs, comparisons, life situations, process, payouts, checklists – searchable via the magnifier button in the header.

Frequently asked questions

How does the tax credit work?

20% of the premium paid into pension insurance (up to an annual cap) can be reclaimed from the personal income tax you have actually paid – the tax authority transfers the amount directly onto the contract, so it also grows your savings.

When can I access the money?

The goal is retirement: the contract is tied to the retirement age or actual retirement. Early access means repaying the credits – the lock-in is exactly what protects the savings from being spent along the way.

What if I cannot pay the premium?

Most products allow suspension, reduction or paid-up status – flexibility rules differ even within products, so we compare this up front.

Which costs should I watch?

The key metric is the TKM (total cost indicator), which makes products comparable. Beyond that, the underlying funds and bonus terms matter – I present them all in plain words.

Should I choose a classic or unit-linked form?

A question of risk appetite and time horizon: a longer horizon can carry more equity exposure, a shorter one calls for a more cautious structure. In unit-linked policies the client bears the investment risk – we discuss this openly and tailor the plan to your rhythm.
All questions – FAQ page (36) →

Useful documents

Product summary – on one pagePDF
Download ↓

More aids – checklists and guides – on the Resources page.

Gyula, Irén and Rózsi started early – compound interest has been working for all three ever since.

Request a quote – the first step is a 20-minute call.

As an independent broker I make insurers compete for you – not the other way round. My advice costs you nothing.

Book an appointment

The broker

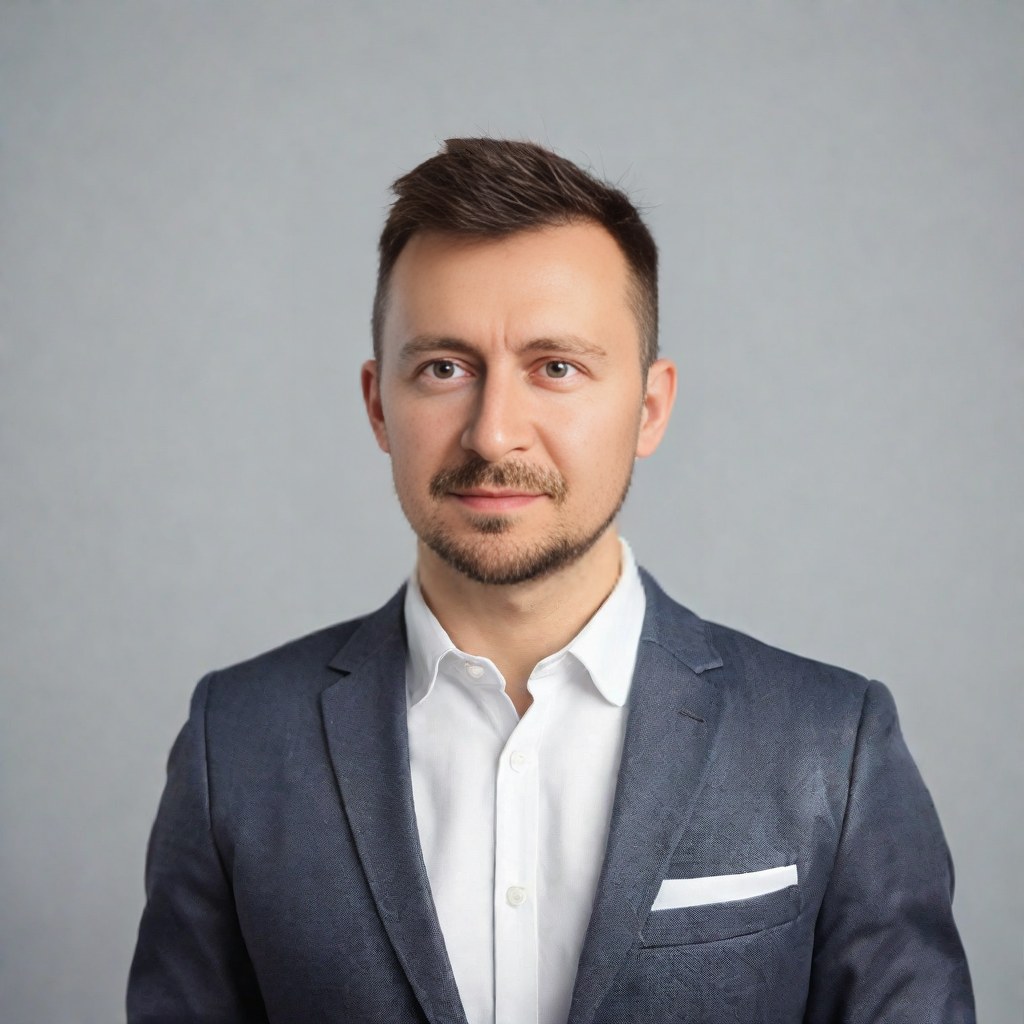
Portrait of Emánuel Dávid Tukacs, independent insurance broker

nyugdij.biz is the information and quote-request page of Emánuel Dávid Tukacs, independent insurance broker. As a broker I act on the client's behalf: I compare offers from several insurers, and the decision always rests with the client. My advice is free of charge to the client – the brokerage remuneration is paid by the insurer.

MNB registration number: 114063010758 (verifiable in the MNB institution register) · Operating as a partner of Eurorisk Biztosítási Alkusz Kft. · Main site: tukacs.com · Privacy notice